Published September 7, 2026
How to Buy Your Next Home When You Have a Home to Sell in West Seattle
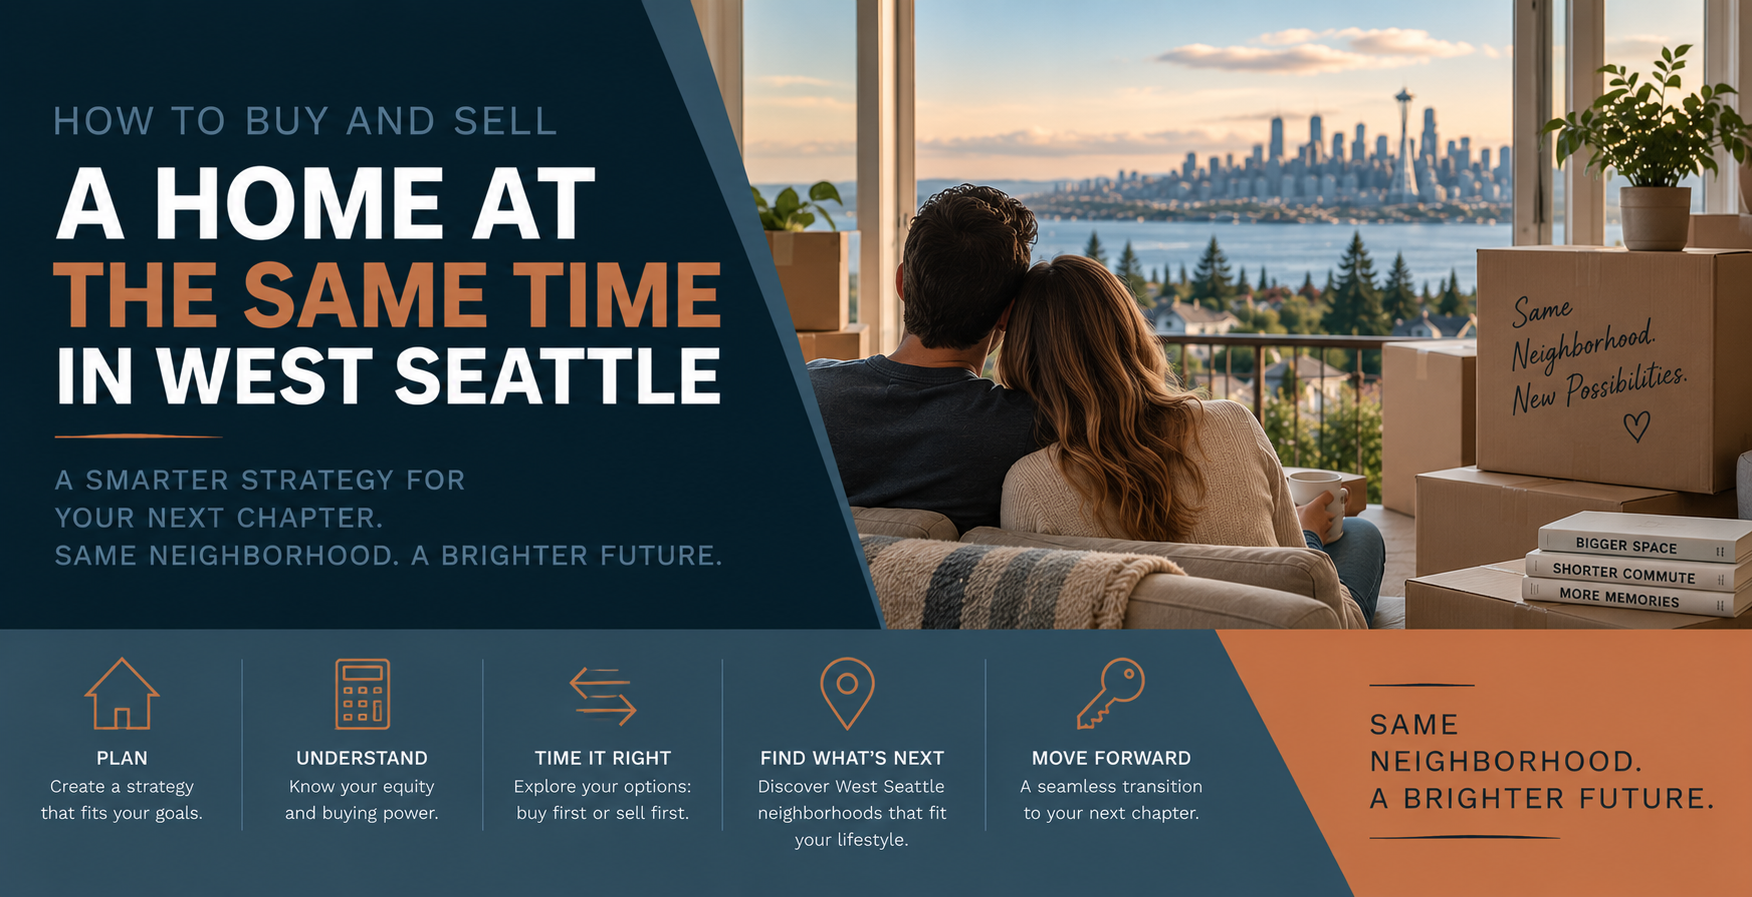
You'd move if you knew exactly how to make the pieces work.
But there's one problem:
You already own a home.
For many West Seattle homeowners, that's where the idea of moving up gets complicated.
You may have substantial equity and a home you could sell—but that creates a long list of questions:
Do we sell first? What if we can't find another house? Can we buy before we sell? What happens to our current mortgage? How much will our new payment be?
This is why move-up buying isn't simply a home search.
It's a planning exercise.
And the strategy should begin well before you find the house you want.
First: Understand Why You're Moving Up
"Move-up buyer" doesn't necessarily mean someone looking for a mansion.
Often, homeowners simply want a home that fits their lives better.
You may want:
- Another bedroom
- A dedicated home office
- Better entertaining space
- A yard
- More walkability
- A different West Seattle neighborhood
- Less maintenance
- A better layout
Before discussing financing or timing, identify the problem your next home needs to solve.
Otherwise, it's surprisingly easy to buy a larger house without actually improving your life.
Step 1: Determine What Your Current Home Could Sell For
Your existing home is the starting point.
Before shopping seriously, understand:
- Estimated market value
- Remaining mortgage balance
- Approximate selling expenses
- Potential net proceeds
- Available equity
For many longtime West Seattle homeowners, equity may become a major component of the down payment on their next property.
Until you understand that number, it's difficult to accurately evaluate your buying power.
Step 2: Understand Your New Monthly Payment
This is where many potential move-up buyers stop.
They compare their current mortgage payment—often tied to a lower rate—with a hypothetical payment at today's rates.
The difference can be uncomfortable.
But don't stop the analysis there.
Your down payment may be significantly different this time because of the equity you've accumulated.
You also need to consider:
- Purchase price
- Down payment
- Mortgage rate
- Taxes
- Insurance
- HOA dues, if applicable
- Maintenance
The question isn't whether the new payment is higher.
The question is:
Does the complete financial picture make sense for the lifestyle improvement you're getting?
Step 3: Decide Whether To Buy First or Sell First
There's no universal answer.
Selling First
Selling first can provide greater certainty about your available proceeds and remove the responsibility of carrying two homes.
But it creates another concern:
Where do we live if we haven't found the next home?
Depending on the transaction and market conditions, there may be strategies to create more flexibility.
Buying First
Buying first can make the transition easier because you've secured your destination before giving up your current home.
However, you'll need to understand whether your finances allow it and what financing options may be available.
The right sequence depends on your equity, financing, risk tolerance, inventory, and timeline.
Step 4: Know What You're Waiting For
One of the biggest fears among move-up buyers is:
"What if we sell and can't find anything we like?"
That's why we don't want you blindly putting your home on the market and hoping everything works out.
Beforehand, we can study:
- What your next-home budget buys
- Which neighborhoods fit your goals
- How frequently appropriate homes become available
- How competitive those homes tend to be
- Which compromises you're willing to make
The clearer your criteria become, the easier it is to design the sequence.
Step 5: Build a West Seattle-Specific Search Strategy
Moving from one West Seattle neighborhood to another can create a surprisingly significant lifestyle change.
Perhaps you're moving from a quieter residential pocket and want the walkability of North Admiral.
Maybe you love your current location but want more space nearby.
Or perhaps you're willing to trade square footage for Alki access or a view.
This is where hyperlocal knowledge becomes especially valuable.
We aren't simply asking:
"How many bedrooms?"
We're asking:
"What do you want your everyday life to feel like after this move?"
Step 6: Plan the Sale Around the Purchase—and Vice Versa
Your sale and purchase shouldn't be treated as unrelated transactions.
They're two parts of the same move.
A coordinated plan may consider:
- When to prepare your current home
- When to begin touring
- Financing readiness
- Closing timelines
- Possession
- Moving logistics
- Offer competitiveness
- Contingency strategies
The objective is to reduce the number of variables you're trying to solve at once.
Don't Wait Until You Find the Dream House
This may be the most important advice in this article.
The worst time to figure out your move-up strategy is after you've fallen in love with another house.
Suddenly everything feels urgent.
You're trying to understand your equity, financing, sale preparation, offer strategy, and moving timeline while competing for a property you desperately want.
Instead, do the planning first.
Then when the right home appears, you know what's possible.
What If You're 6–12 Months Away?
That's actually an excellent time to start.
There may be nothing you need to do immediately.
But you can understand:
- What your current home is worth.
- What you'd likely net from selling.
- What your next home could cost.
- What the monthly payment could look like.
- Whether selling or buying first makes sense.
- Which West Seattle neighborhoods fit the lifestyle you're after.
Now you're not wondering whether you could move.
You have a roadmap showing what it would take.
Final Thoughts
For move-up buyers, the hard part usually isn't finding beautiful homes online.
It's coordinating the transition between the home you have and the life you want next.
That's why we approach move-up buying as a strategy—not a transaction.
You don't need to decide today that you're moving.
You just need enough information to understand whether the move is possible.
Let's Build Your Move-Up Plan
If you own a West Seattle home and you're wondering how you could buy your next home without making the process unnecessarily stressful, let's map it out.
We'll look at your current home's potential value, equity, next-home goals, timing, and the possible paths between the two.
Book a call with The Pearsall Team:
Schedule Your 30-Minute Move-Up Strategy Call
FAQ
How do I buy another house before selling mine?
Whether buying first is possible depends on your equity, income, financing, and overall financial position. A lender and real estate advisor can help evaluate available strategies before you begin shopping.
Should I sell my West Seattle home before buying another one?
It depends on your finances, risk tolerance, market conditions, and available inventory. Selling first can provide financial certainty, while buying first may provide more certainty about where you'll live next.
Can I use equity from my current home to buy my next home?
Homeowners commonly use proceeds from their existing home toward their next purchase. The appropriate structure depends on when the equity becomes available and your financing plan.
When should I start planning a move-up purchase?
Ideally, before you find the next house. Starting several months in advance gives you time to understand your equity, financing, sale preparation, neighborhood options, and timing.